A pipe can leak behind a wall for hours before it becomes visible. By the time flooring buckles, drywall stains, or a ceiling begins to sag, the property damage may already be expanding. This Maryland insurance restoration guide explains what to do first, how the restoration process typically works, and how to keep your claim supported by clear, timely documentation.
For homeowners, property managers, and commercial owners, the priority after a covered loss is not choosing finishes or estimating final repair costs. It is stopping further damage safely, documenting the condition of the property, and beginning professional mitigation before moisture, smoke residue, or storm exposure creates a larger problem.
What to Do Immediately After Property Damage
Start by protecting people. If there is an active fire risk, structural instability, sewage contamination, electrical hazard, or suspected gas leak, leave the area and contact the appropriate emergency service or utility provider. Do not enter standing water near electrical equipment, damaged ceilings, or areas with unstable building materials.
Once the property is safe to access, take practical steps to limit additional loss. Insurance policies commonly require property owners to take reasonable action to protect the building after a loss. That does not mean performing unsafe repairs or discarding evidence. It means acting promptly and keeping a record of what happened.
When possible, take these early actions:
- Photograph and video the affected rooms, exterior damage, damaged contents, and the apparent source of loss before major cleanup begins.
- Report the loss to your insurance carrier and record the claim number, adjuster contact information, and the date and time of each conversation.
- Arrange emergency mitigation for water intrusion, fire and smoke damage, storm exposure, or other conditions that can worsen quickly.
- Save invoices, receipts, estimates, moisture reports, photos, and written communications in one claim file.
If a roof is damaged during a storm, temporary protection may be necessary to keep rain from entering the structure. If a supply line fails, water extraction and drying should begin as soon as possible. Waiting for an adjuster inspection before addressing active water or exposure can increase the scope of damage. The best approach is to document conditions thoroughly while having qualified professionals stabilize the property.
Maryland Insurance Restoration Guide: From Loss to Repair
Insurance restoration is not a single repair visit. It is a coordinated process that usually moves through emergency response, assessment, mitigation, claim documentation, reconstruction, and final completion. Each stage affects the next, especially when concealed moisture, damaged building systems, or code-related repair requirements are involved.
1. Stabilize the loss
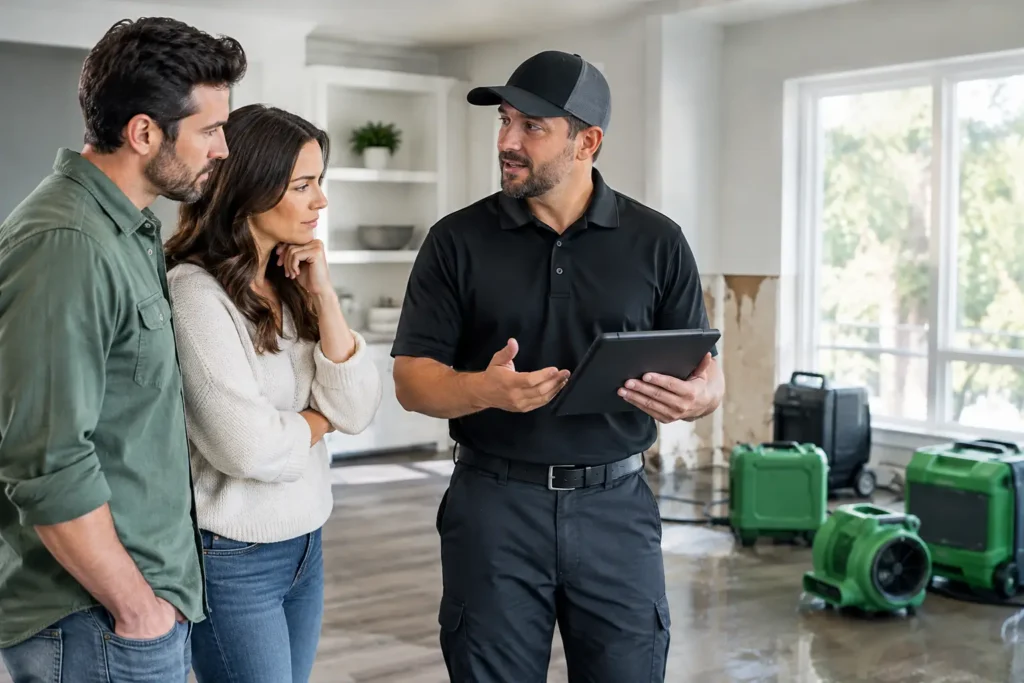
Mitigation is the work that prevents damage from spreading. For water losses, that can include water extraction, removal of unsalvageable materials, moisture mapping, structural drying, and humidity control. For fire losses, it may include board-up, odor control, smoke residue cleaning, contents handling, and securing damaged openings.
Mitigation is different from reconstruction. Drying a wall cavity, removing wet insulation, or placing temporary roof protection addresses the immediate condition. Rebuilding drywall, replacing flooring, reinstalling cabinets, and painting are reconstruction tasks completed after the property is dry, safe, and ready for repairs.
2. Document conditions before and during work
Good documentation creates a clear record of both the original damage and the work required to restore the property. Photos alone can be useful, but a restoration file may also include moisture readings, thermal imaging, 360-degree imaging, drying logs, equipment records, itemized estimates, and photographs taken during demolition.
This matters because visible damage is not always the full scope. Water can travel beneath flooring, through insulation, and along framing. Smoke can affect contents and HVAC pathways beyond the room where the fire occurred. Storm damage may involve roofing materials, gutters, siding, interior finishes, and hidden water intrusion.
A professional restoration contractor should explain what is being documented, why materials need to be removed or dried, and what the findings mean for the next phase of the project. Clear communication helps property owners make informed decisions and gives adjusters a more complete basis for evaluating the loss.
3. Coordinate the inspection and estimate
Your insurance carrier may assign an adjuster to inspect the damage and prepare or review an estimate. The adjuster’s role is to evaluate the claim under the terms, limits, deductibles, and exclusions of the policy. A contractor’s role is to assess the physical work needed to mitigate and restore the property.
These scopes do not always align on the first review. A difference may arise because damage was concealed, materials changed after demolition, moisture remained in a building assembly, or a repair requires related work to restore the property properly. This is where detailed contractor documentation can be especially valuable.
Avoid assuming that an initial estimate is automatically the final scope. If new damage is discovered during the restoration process, it should be photographed, documented, and communicated before additional work proceeds when practical. The carrier determines coverage, but well-organized evidence can help support a request for review.
4. Move from mitigation to reconstruction
Reconstruction should begin after the structure is properly dried, cleaned, and cleared for repair. Depending on the loss, the work may involve drywall, insulation, flooring, trim, painting, cabinets, plumbing, electrical, HVAC components, roofing, siding, gutters, or structural repairs.
This phase is where a full-service contractor can reduce coordination problems. Instead of relying on separate vendors for demolition, drying, roofing, electrical work, and finish repairs, property owners can benefit from a single project team managing the sequence. That matters when one delayed trade can hold up the entire schedule.
The right repair approach depends on the building, the extent of damage, material availability, and policy requirements. For example, a localized plumbing leak may only require drying and limited finish repairs. A storm-related roof failure with widespread interior water intrusion may require emergency protection, roof repairs, insulation replacement, drywall work, flooring removal, and repainting across several rooms.
Common Claim Challenges and How to Avoid Delays
Most delays are not caused by one issue. They tend to result from incomplete documentation, missed communication, unresolved scope differences, delayed approvals, unavailable materials, or repairs starting before the damage is fully assessed.
Keep your claim organized from day one. Maintain a dated log of calls, inspections, approvals, payments, and work completed. Ask questions when a scope is unclear, including whether the estimate addresses mitigation, reconstruction, contents, and required related repairs. If you receive a payment, understand whether it is an initial payment, depreciation-related payment, or payment tied to a specific portion of the work.
Do not discard damaged materials, contents, or records until the carrier has had a reasonable opportunity to evaluate them, unless they create a health or safety concern or must be removed during necessary mitigation. In those cases, photographs, inventory records, and contractor documentation become even more important.
Property owners should also be careful with cosmetic upgrades. Insurance restoration generally focuses on returning covered damage to its pre-loss condition, subject to policy terms. If you decide to upgrade flooring, cabinetry, fixtures, or finishes during reconstruction, separate the restoration scope from elective improvement costs. This keeps claim discussions clearer and allows the project to move forward without confusion.
Why Restoration Standards Matter
A fast response is valuable only when the work is performed correctly. Incomplete drying can contribute to odors, material deterioration, and mold concerns. Improper smoke cleaning can leave residue behind. Rushed repairs can conceal conditions that should have been addressed before finishes were installed.
IICRC-based restoration protocols, moisture monitoring, controlled demolition, proper containment when needed, and OSHA-compliant jobsite practices help protect the property and the people inside it. For roofing and storm losses, qualified inspections can also help identify damage patterns that are not obvious from ground level.
Apollo Construction & Renovation Corp. approaches insurance restoration as a complete recovery process, combining emergency mitigation, detailed documentation, skilled reconstruction, and organized communication with property owners and insurance professionals. The goal is not simply to make damage less visible. It is to restore the building safely, efficiently, and with workmanship that supports long-term performance.
When to Call a Restoration Professional
Call promptly when water is actively entering the property, materials are wet, smoke or soot is present, a roof opening is exposed, sewage has affected the building, or damage may be concealed behind walls, ceilings, or flooring. Early assessment is particularly valuable for commercial properties, multifamily buildings, and HOA-managed communities, where one event can affect multiple units or interrupt operations.
The right next step after a property loss is a documented, professional response that protects the structure while the claim takes shape. Preserve the evidence, address active damage safely, and work with a restoration team that can carry the project from emergency stabilization through final repairs.
Every property and insurance policy is different. Contact Apollo to discuss the work your property may need; your insurer determines coverage.